










Most budgets fail at line one. People guess what comes in. A guess of $2,400 against a real $2,150 leaves a $250 hole, and that hole gets filled with a late fee or a credit card. A monthly income and benefits record fixes the guess with a number you wrote down.
This article explains how people commonly organize that record. It is general education, not advice about your own money or benefits. Programs change, so confirm details with the agency that runs your benefit.
Why a Monthly Income and Benefits Record Matters
The Consumer Financial Protection Bureau (CFPB) runs a toolkit called Your Money, Your Goals. One of its tool categories is Tracking Income and Benefits, sitting next to tools for paying bills and getting through the month. The idea is plain: keep track of what comes in and what goes out.
A written record also catches trouble early. Say a deposit is $40 short, or a paycheck drops because of fewer hours. Without a record, you notice when the rent bounces. With one, you see it the day it lands, and you have dates and amounts ready if you need to call a bank or an agency.
Reporting Wages If You Receive Social Security Benefits
If you get Social Security benefits and also work, tracking is not only for your own budget. The Social Security Administration (SSA) says regularly reporting wages helps prevent overpayments. An overpayment means you were paid more than you were owed, and the agency may later need to recover it.
For people who receive Supplemental Security Income (SSI), the guidance is to report wages every month, within six days after the month ends. That is a short window. Example: wages for March are due by about April 6. Many people set a recurring calendar reminder, and SSI recipients can sign up online for a monthly email or text reminder.
The SSA lists several ways to report:
- Online through the my Social Security wage reporting service, for people who get SSDI or SSI or act as a representative payee. You need your own my Social Security account.
- By telephone or mobile app, for SSI recipients and certain family members, sponsors, or representative payees.
- By fax, by mail, or by bringing pay stubs to a local Social Security office.
Changes in work activity can be reported by calling 1-800-772-1213. The TTY line is 1-800-325-0778. One caution from the SSA itself: some of its wage-reporting information may be historical. Check the current rules on the official SSA site before you act on this article or any single page.
Building a Simple Monthly Tracker
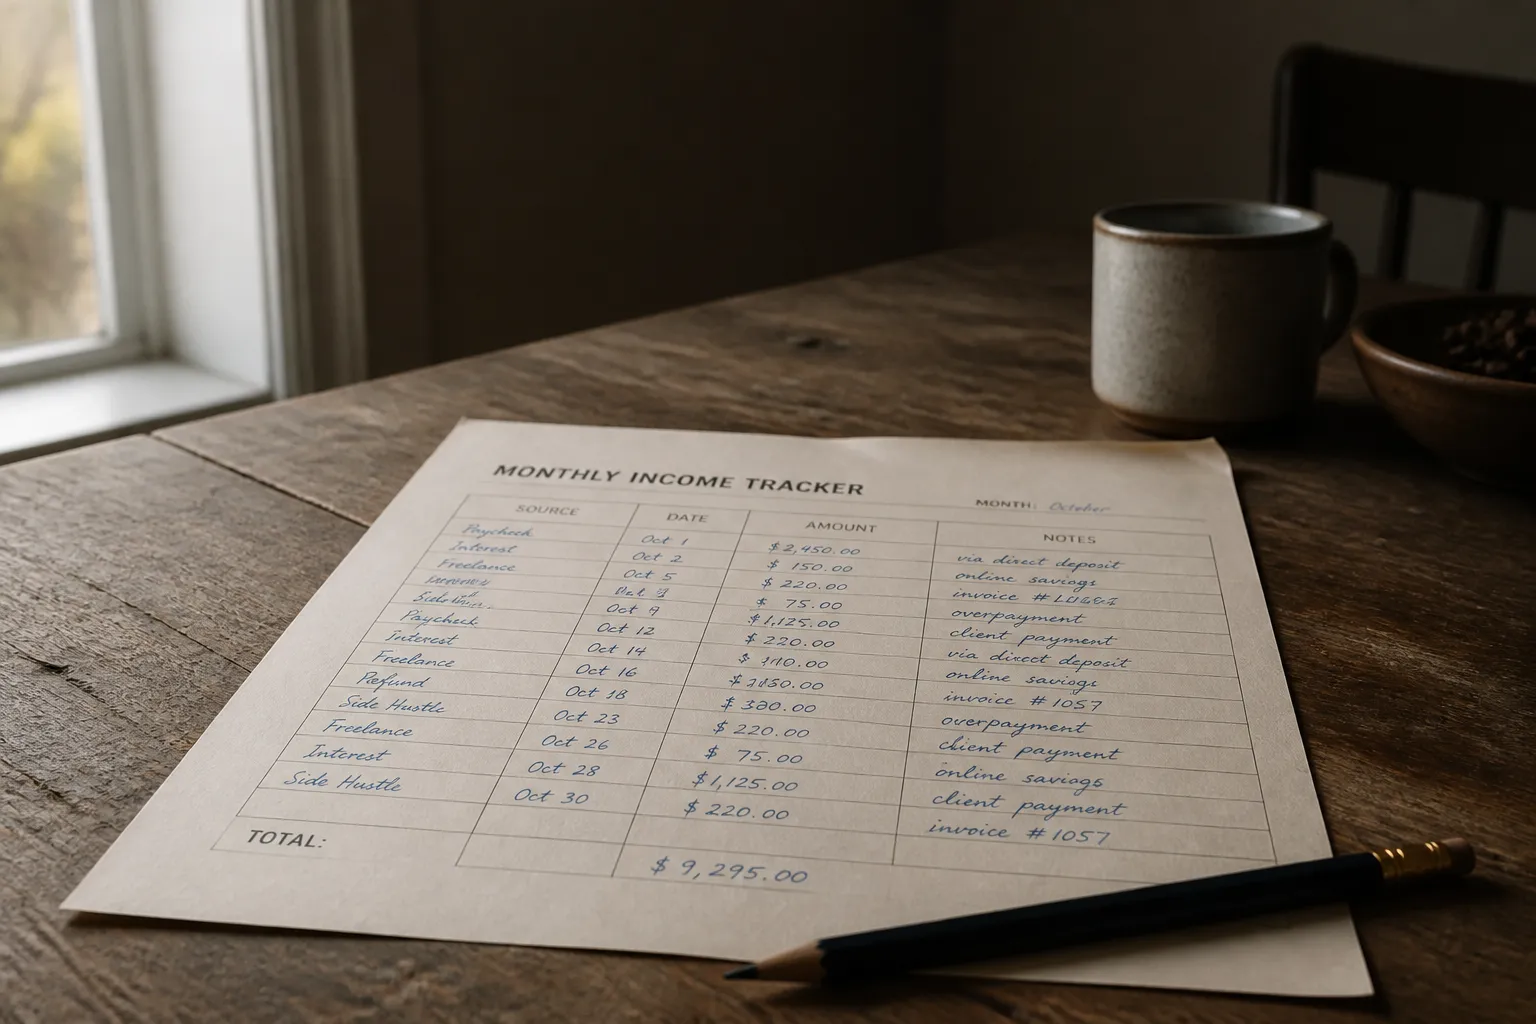
You do not need software. A notebook works. Use the same layout every month so the months can be compared at a glance.
- Write the month at the top.
- List each income source on its own row: a paycheck, a benefit payment, anything else.
- Record the date each payment arrived.
- Record the amount actually received, not the amount you expected.
- Add a note for any change, such as fewer hours or a late deposit.
- Total the column.
Then compare the record with your bank statement. Each deposit should match a row. If one does not, you have found something worth a phone call. The sources I reviewed give no detailed method for this step, so treat it as a habit to adapt, not a formal procedure.
Keep the paper trail together: wage-reporting confirmations, pay stubs, and benefit notices. Dry as it sounds, that folder is what settles a dispute months later.
Questions to Ask Each Month
A short checklist keeps the routine honest. Ask these once a month, at the same time you update the tracker:
- Which benefits do I receive, and does that change how often I report wages? SSI has the monthly window. SSDI rules may differ.
- Which reporting method can I use? Online, phone, app, mail, fax, or an office visit are not open to everyone.
- Is my reminder set, and is my my Social Security account active if I report online?
- Is the office or method I plan to use still current?
If any answer is "I don't know," that is the item to look up on the official SSA site or ask the agency about directly.
Where Current Information Is Thin
Be skeptical of any tidy system, including this one. The CFPB's income and benefits worksheet and its cash flow budget tool could not be read in the material I reviewed, so I cannot describe their exact categories. The FDIC's Money Smart for Adults and a 2026 Federal Trade Commission planning article were available only as page navigation and headlines.
Several topics are simply not covered:
- Tracking irregular income, such as gig or seasonal pay.
- How earnings change SSI or SSDI amounts.
- Tracking unemployment, veterans, or other public assistance.
- Keeping records for taxes.
For those, go to the agency that pays the benefit or a qualified professional. They can answer for your situation. A spreadsheet cannot.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


