










A payment plan does not make a medical bill smaller. It makes the bill slower. That is useful if the number is right and the terms are clean, and expensive if neither is true. So the budget starts before the first payment, with a few checks that cost nothing but a phone call.
Confirm what you owe before you plan around it
The Consumer Financial Protection Bureau (CFPB) says to confirm you actually owe the amount charged. That means looking for billing errors, making sure insurance was applied correctly, and checking for duplicate charges or a bill meant for someone with a similar name. [3] A corrected balance is the cheapest raise you will ever get.
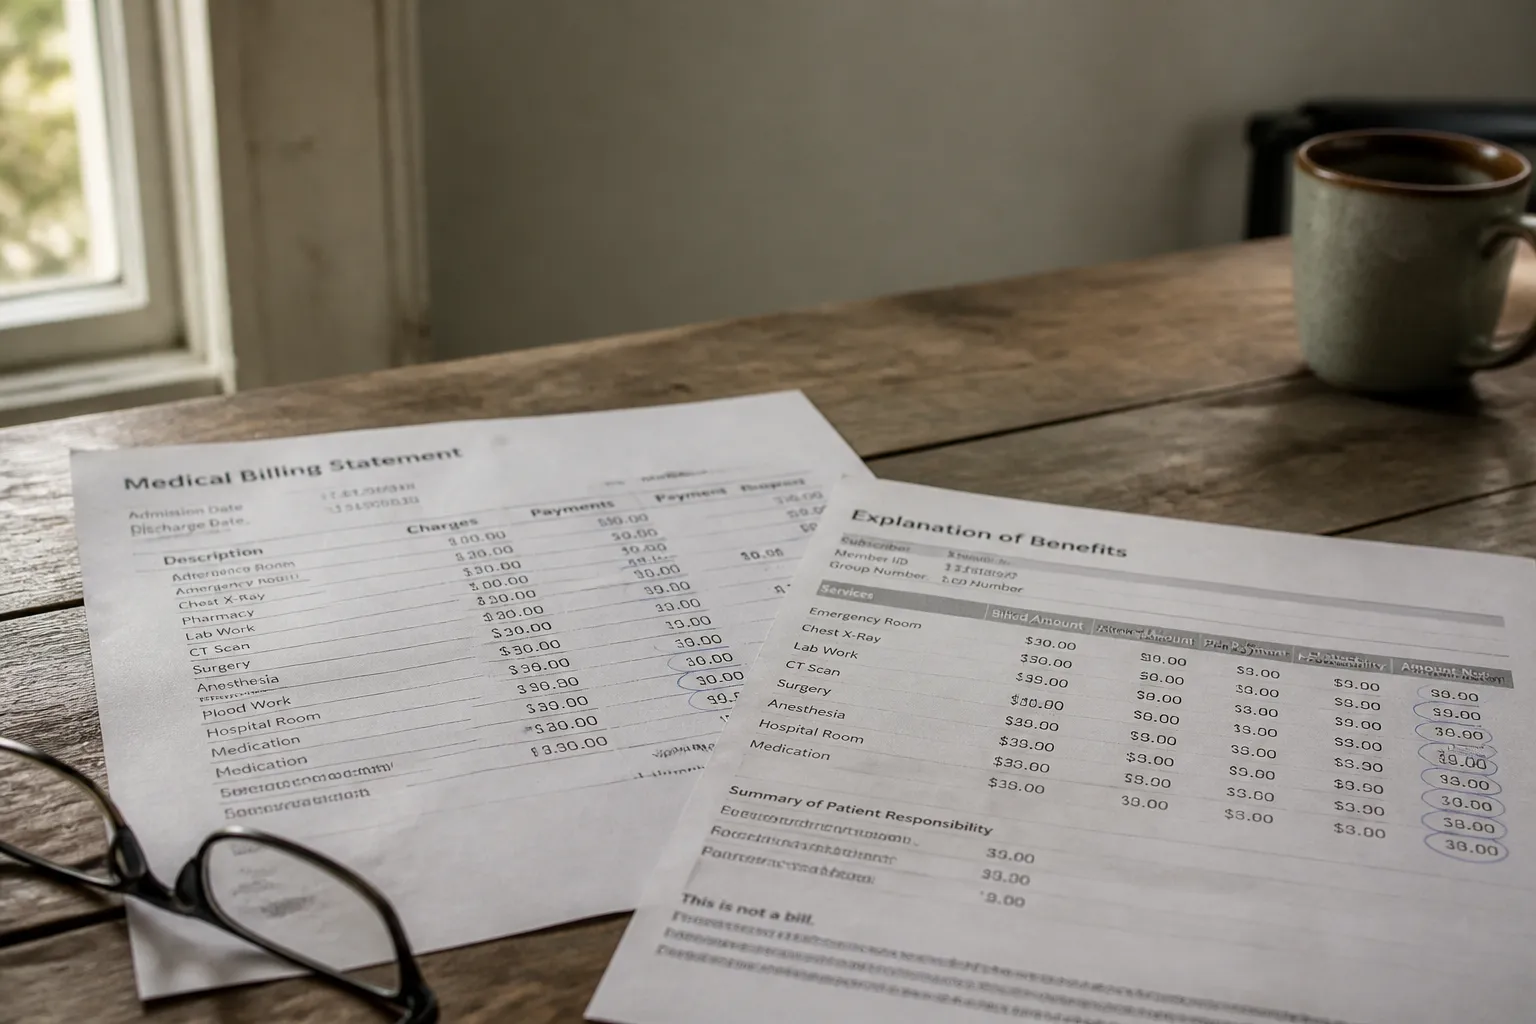
Ask the billing office for an itemized list of charges. Put it next to your insurer's explanation of benefits, which is the statement showing what the plan covered and what it says you owe. Circle any line you do not recognize. Keep copies of everything, including what you have already paid. Use the contact information on the statement and ask two things: who can answer questions about the balance, and when the next payment is due. A budget needs an exact figure and an exact date.
Check financial assistance and charity care first
Before you accept a payment plan or a medical credit card, ask whether the provider offers financial assistance or charity care, and whether you qualify. The CFPB lists this as a first step because assistance can lower the total, while a plan only spreads it out. [1][3] Also ask what your insurance covers for this bill. A denied claim or a wrong rate can move the balance more than any schedule will.
Applications usually ask about income and household size, so gather pay stubs, tax documents, and bank statements ahead of time. The CFPB pages used for this article do not walk through application steps. Ask the billing or financial counseling office for the process, the deadline, and how decisions are made, and ask for it in writing.
Here is a quick order of operations. Do these before you sign anything:
- Get the itemized bill and compare it with the explanation of benefits.
- Dispute anything wrong, in writing, and keep copies.
- Ask about financial assistance or charity care and what insurance should cover.
- Only then ask what payment options exist.
Understand the payment options before you commit
Some providers offer medical credit cards or installment plans. The CFPB says these carry downsides, risks, and costs, and that a medical credit card is not the same as a regular credit card. Medical financing plans differ from both. [1] The CFPB's research also found that patients may pay more than they otherwise would with these cards and loans. [2]
Deferred interest deserves a hard look. The CFPB has studied these offers. [2] In general, interest can be charged from the original purchase date if the promotional period ends with a balance left. The sources here do not explain the mechanics, so ask the provider or issuer to explain in plain words when interest starts and what happens if you are one payment short. Get the total cost in dollars, not just the monthly figure.
One more question: does the provider offer a plan directly? The CFPB reports that informal, low- or no-cost provider plans have largely been replaced by financing products marketed to providers and patients. [2] A direct plan with no interest fits a budget better. It is worth asking before you take the financing brochure.
Build the monthly budget around a realistic payment
Now do the arithmetic. Take the corrected balance, add any interest and fees, and divide by the number of months. Say the corrected bill is $2,400 and the plan runs 24 months with no interest. That is $100 a month. If the plan adds $300 in fees, the total is $2,700 and the payment is $112.50. Put that figure in the budget with rent, food, and utilities. If it does not fit, trim flexible spending first, not the fixed bills.
If the offered schedule is too steep, say so before you miss a payment. The CFPB advises asking about plan options before the debt gets harder to manage. Doing nothing can bring late fees, interest, collections, lawsuits, garnishment, and lower credit scores. [3] A call now is easier than a call after a collector's letter.
Before you commit, run these checks on the number:
- Is the payment based on the corrected balance, not the original one?
- Does it include every fee and any interest?
- Can you pay it in your leanest month, not your average one?
- Do you have a written record of each payment and its confirmation?
Know the protections and what they mean for credit reports
Federal and state law may reduce what you owe and shield you from some collection and credit reporting practices. [3] Details vary by situation and place, and the sources here give no dispute deadlines. Check the CFPB and your state attorney general's consumer pages for current rules.
Credit reporting has shifted. The three nationwide credit reporting companies removed paid medical debts and medical debts less than a year old, and removed medical collections under $500 effective April 11, 2023. The CFPB estimated roughly half of people with medical debt on their reports would see it removed. [7] A CFPB rule issued January 7, 2025 would have limited medical debt reporting further, but a federal court in Texas vacated it on July 11, 2025. [5][6] So confirm current practices with the credit bureaus directly. Nothing here promises any credit score result.
The No Surprises Act also helps protect people from certain unexpected bills, including surprise bills for emergency services from out-of-network providers. [7] If your bill looks like that, raise it with the billing office and your insurer before setting up a plan. This article is educational only. For your own situation, a consumer protection office, legal aid group, or other qualified professional can give advice that fits.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


