










A tenant screening report and a credit report can both affect a rental application, but they answer different questions. A credit report centers on borrowing. A tenant screening report is a broader file assembled for a housing decision. It may include credit information, rental records, court records, employment details, and other background data. Knowing which report was used can help you request the right file and look for the right errors.
Start with the basic distinction
A credit report is a record of your credit activity and current account status. It can show loans, credit cards, payment history, balances, and accounts that are open, closed, or in collection. It is designed to help a user evaluate how you have handled credit.
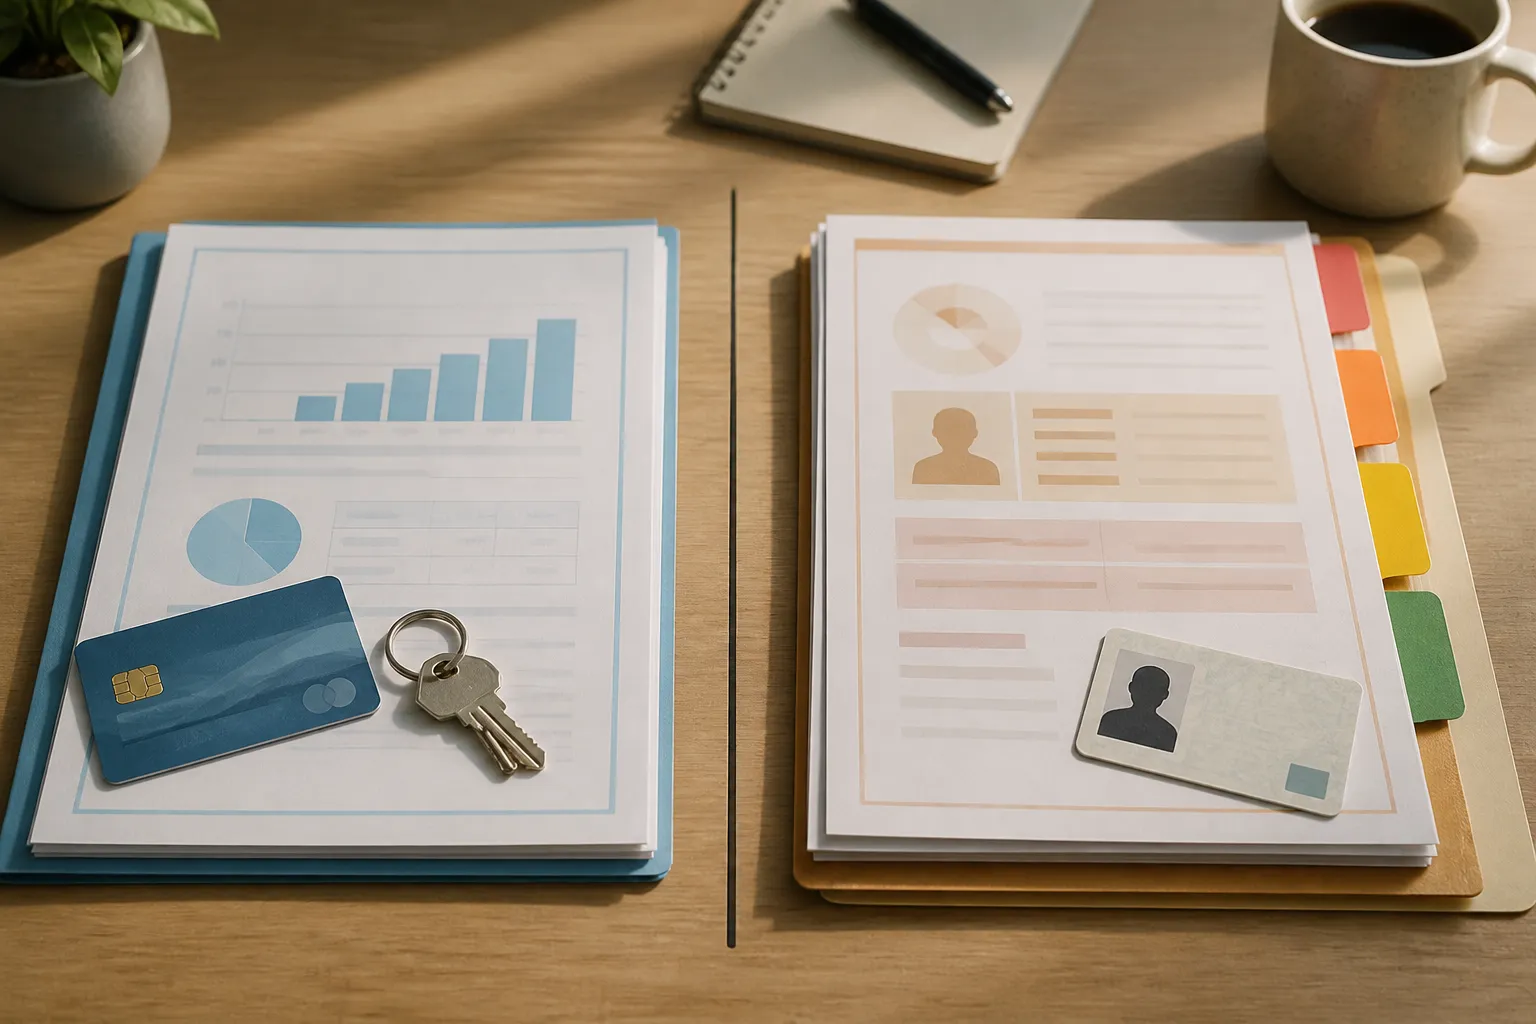
A tenant screening report is built for a landlord's decision. The Consumer Financial Protection Bureau describes it as different from a credit report. Depending on the screening company and the landlord's criteria, the file may contain credit data, rental history, eviction and civil court records, employment verification, criminal history where permitted, registry searches, or a risk score.
That means a screening report may contain a credit report or credit-related information without being the same thing as a credit report. One is mainly about credit accounts. The other can combine several types of records into a housing-focused package.
- Ask what type of report was used. A denial, higher rent, larger security deposit, or required co-signer may have been based on a tenant screening report, a credit report, or both.
- Identify the company behind the report. There is no single tenant screening report used by every landlord. Specialty reporting companies differ in the records they collect and the way they present them.
- Request the report that mattered. The management company can tell you which consumer reporting company it uses. The CFPB also keeps a list of consumer reporting companies, including specialty agencies.
- Read the decision notice carefully. If a report played a role in an adverse action, the notice should identify the company that supplied it and explain how to contact that company.
- Check the facts, not only the conclusion. Look at names, dates, account details, court outcomes, and duplicate entries. A score or recommendation may not explain which record caused concern.
- Save supporting documents. Keep a copy of the report, the landlord's notice, and records that show an error, such as a dismissal or proof that an account belongs to someone else.
- Dispute inaccurate information with the reporting company. The company generally has 30 days to investigate, although some investigations can take 45 days and state rules may differ.
Who creates each report
Credit reporting is concentrated among three national credit bureaus. Tenant screening is more fragmented. Many specialty companies produce these reports, and some may resell or combine data from other sources. The landlord's chosen vendor therefore affects what appears in the file.
This difference matters when you try to review your information. Checking one credit report does not necessarily show every tenant screening record that a landlord might see. Start by asking the property manager for the screening company's name, address, and phone number. If you already received an adverse action notice, those details should be included there.
Requesting a copy of your own consumer report does not hurt your credit scores. Some companies must provide free reports on a regular schedule, and the CFPB says companies required to provide an annual free report must generally respond within 15 days of receiving a request. The exact process can vary by company and report type, so check the company's official instructions.
What an adverse action notice tells you
An adverse action is a negative housing decision connected to a consumer report. It can include a denial, a demand for a co-signer, or terms that are less favorable than those offered to other applicants, such as a larger deposit or higher rent. The CFPB explains what to look for after a rental application is denied.
The notice should identify the consumer reporting company, provide contact information, explain your right to dispute inaccurate information, and tell you that you can request a free copy of the report if you ask within 60 days. A landlord generally may provide this notice in writing, orally, or electronically, although keeping a written record is useful for understanding what happened.
Ask the landlord what information drove the decision. The notice may identify the reporting company but not explain whether the concern involved a payment history, an eviction entry, a criminal record, or a screening score. A question about the specific information relied on can help you focus your review.
Errors that deserve close attention
Eviction records require careful reading. A court filing is not the same as a judgment, and a dismissed case should show that it was dismissed. A report that lists the filing but leaves out the final outcome can present an incomplete picture. Also check for the same eviction appearing more than once.
Review names, former addresses, dates of birth, employer information, account numbers, and case numbers. Similar names can cause records to be matched to the wrong person. Old or incomplete information can also make a housing search harder. The CFPB's guidance on reviewing a rental background check recommends asking for the report used in the decision when possible.
Automated scores and recommendations can make this review harder. Specialty screening companies often use automated tools, which may include artificial intelligence, to sort information or produce a recommendation. A score may summarize a decision without showing which underlying records were used. Advocates have raised concerns that hidden errors or disparities can pass through these systems. Treat the score as a signal to investigate, not as an explanation by itself.
How to organize a dispute
Begin with the reporting company named in the notice or identified by the landlord. Ask for the complete report and the instructions for disputing information. Mark each disputed item precisely. For example, identify an eviction case number, explain that the case was dismissed, and attach a document showing the final disposition if you have one.
Keep your request focused and retain proof that you sent it. The reporting company generally must investigate within 30 days, with some investigations taking up to 45 days. If the company updates the report, request a corrected copy and ask how the landlord will receive the correction. The sources do not establish one universal process for every screening company, so follow the company's official dispute instructions.
State rules can add protections or set different deadlines for screening fees, criminal records, eviction records, or disputes. Federal guidance does not provide a single state-by-state answer. For a specific housing dispute, consider checking your state or local housing agency, a housing counselor, legal aid office, or qualified attorney. This article is educational information, not personal financial or legal advice.
What these reports cannot tell you
Public guidance does not establish one standard retention period for tenant screening records or one fixed lookback period for every report. It also does not provide a universal formula for a screening score. A particular score does not have one meaning across all companies or landlords.
Before applying, you can ask which screening company will be used, what types of information it checks, and how the landlord handles adverse action notices. After a negative decision, ask which report was used and request the free copy within the 60-day window if it applies. Those steps will not guarantee a housing outcome, but they can show you which records to review and where to direct a correction request.
For federal explanations, review the CFPB's tenant screening guidance and the Federal Trade Commission's tenant background check information. Use official sources for current requirements, especially if your state or local rules may provide additional rights.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


