










A medical bill error can land on your credit report before you have finished sorting it out. That is frustrating, but it is usually fixable. Below is a practical way to find where the mistake sits, pick the right dispute route, write a letter that can be checked, and keep an eye on your reports while you wait. This is general education, not personal financial, legal, or tax advice.
Start with the rules that apply today
Many people have heard that the federal government banned medical debt from credit reports. That was the goal of a 2025 rule from the Consumer Financial Protection Bureau (CFPB), but the U.S. District Court for the Eastern District of Texas vacated it on July 11, 2025, on a joint request from the Bureau and the plaintiffs. The court found the rule went beyond the Bureau's authority under the Fair Credit Reporting Act (FCRA). In plain terms, the rule is not in force, so do not assume every medical debt is off limits.
What still applies is a set of voluntary policies that the nationwide credit bureaus adopted in 2022, with changes taking effect in spring 2023. Under those policies, medical debt that is less than one year delinquent is not reported, paid medical debt is removed, and medical debt under $500 is left off, even if it is unpaid or in collections. Those are useful guardrails. They are not a law, though. Whether state laws that restrict medical debt reporting survive the FCRA is still an open legal question, so check your own state's rules instead of guessing.
Find the layer where the error sits
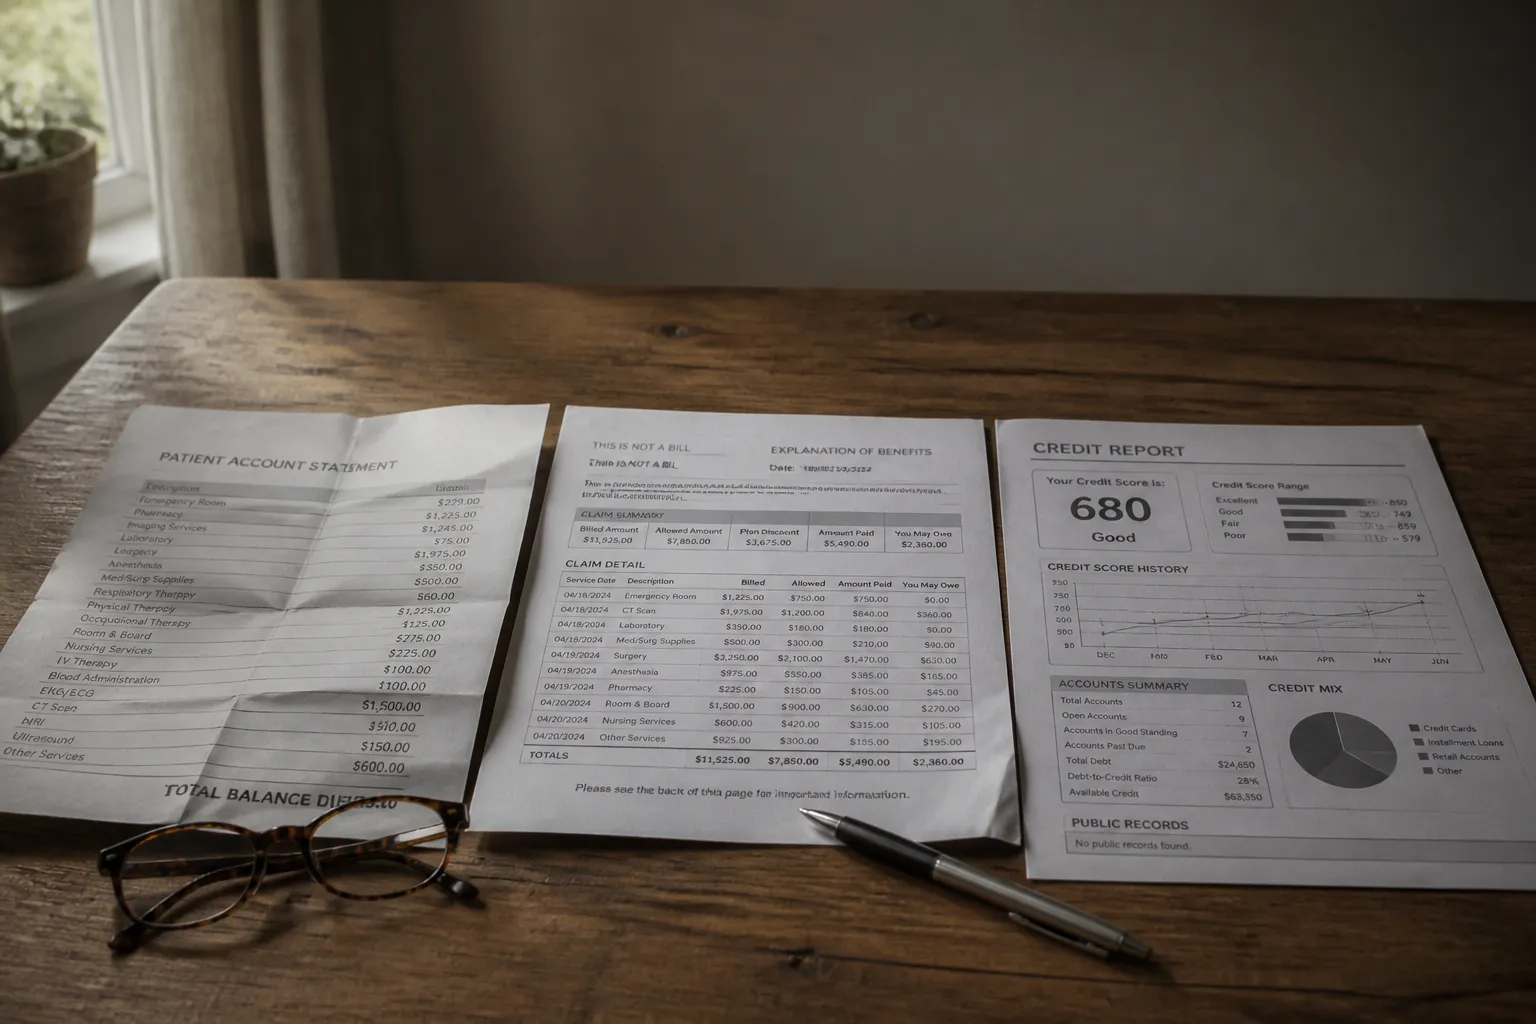
A medical bill moves through several stages. The provider sets its charges. The insurer applies adjustments. You may owe a share as patient responsibility. If the bill goes unpaid, it can become a collection account, and only then does it usually reach your credit report. A mistake can enter at any of these points, and naming the right one keeps your dispute focused.
Most errors fall into three groups. The first is a debt that is not yours at all, such as a wrong patient, a wrong provider or date, a similar name, a mixed file, or identity theft. The second is a wrong amount or wrong payment status. The third is an entry that should not be reported under the bureau policies described above, such as a balance under $500, a paid account, or a debt less than a year past due.
Before you write anything, gather your paperwork and compare. Line up the reported balance against the itemized bill, the explanation of benefits (EOB) from your insurer, your payment receipts, the provider's statements, and any collection letters. An EOB is the insurer's summary of what it paid and what it says you owe. Specific discrepancies, like a charge that appears twice or a payment that never posted, carry far more weight than a general sense that something is off.
Write a dispute that can be verified
Dispute with each credit reporting company that shows the error, which means Experian, Equifax, and TransUnion if all three list it. Then dispute with the company that furnished the information, usually the provider or the collector. The FCRA gives you rights through both routes, and a dispute sent to only one party can leave the error in place elsewhere. The CFPB's guide on disputing credit report errors walks through both paths.
A written dispute should include your full name, address, and phone number. Add the credit report confirmation number if you have one, then list each disputed item with its account number. Explain in a sentence or two why the item is wrong, ask for correction or removal, and attach a copy of the report section with the disputed entries circled. Send copies of supporting documents, never originals. Keep your own file of everything you send.
Certified mail with a return receipt gives you a dated record that the letter arrived. Log every date, phone call, and reply. If the problem involves identity theft or a debt that belongs to someone else, the Federal Trade Commission's IdentityTheft.gov is the federal one-stop site for reporting and recovery. You can use it alongside the bureau dispute.
Use the right route for collections and surprise bills
If the account has gone to a collector, send a written dispute as soon as you can. The CFPB explains that a written dispute protects your rights under the Fair Debt Collection Practices Act (FDCPA) and tells the collector you contest the debt. The FDCPA bars false or misleading statements about the amount, character, or legal status of a debt.
Surprise bills need a second look. The No Surprises Act, effective January 1, 2022, protects people with group or individual health coverage from most surprise medical bills, including many emergency services and out-of-network care at in-network facilities. If you are uninsured or self-pay and your bill is substantially more than the good faith estimate you received, you may have grounds to dispute it. If a collector seeks more than the Act allows for a service, the FDCPA may also come into play. The Centers for Medicare and Medicaid Services (CMS) says Medicare and Medicaid enrollees already have these protections. The Act's independent dispute steps and deadlines are more detailed than the sources here cover, so check current CMS medical bill rights guidance before relying on any timeline.
Protect your credit file while the dispute is open
Check your reports directly and often. The nationwide bureaus offer free weekly credit reports through the central source, so you do not need to open an account with each bureau. Pull the reports while the dispute is pending, see whether the item still appears, and check whether it matches the bureau policies on paid, recent, or small medical debt.
Be realistic about timing. The available sources do not give a fixed deadline for a bureau to investigate, and they do not explain how a pending dispute affects a credit score. No one can promise a score result. Any change depends on many factors beyond a single entry.
If a dispute is denied or the information stays wrong, the sources here offer only general pointers to your rights. The CFPB and your state consumer protection office are good places to ask about next steps. Read the official pages yourself, and consider a qualified professional for your own situation.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


